
DA Davidson Sets $3,000 Micron Target as AI Memory Demand Outpaces Supply
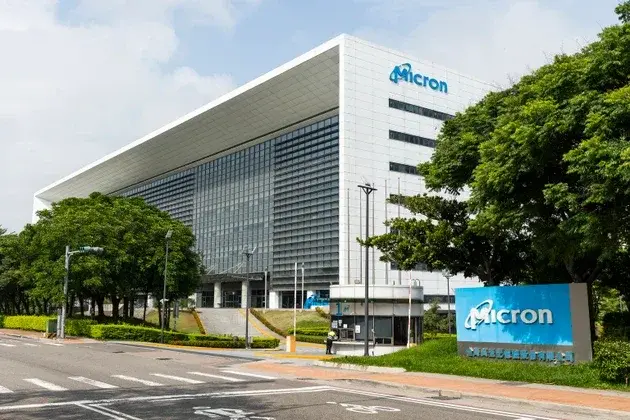
D.A. Davidson raised its price target on Micron Technology to $3,000 from $2,100, citing sustained AI-driven memory demand and undervalued growth potential. The move implies roughly 195% upside from Micron's recent trading price of $1,018. While bulls highlight long-term contracted revenue and a massive U.S. manufacturing expansion, bears warn that new global capacity and Chinese supply could trigger a price peak as early as mid-2027.
Key points
- D.A. Davidson analyst Gil Luria lifted Micron's price target to $3,000, arguing the stock's low valuation multiple fails to reflect its three-to-five-year growth trajectory.
- Micron shares traded at $1,018 before the announcement, implying approximately 195% upside to the new target.
- Barron's notes that Micron has locked in customers for over 75% of its 2027 production, but investors remain wary of a potential memory price downcycle.
- Citi analyst Atif Malik predicts the earliest memory price peak could occur in mid-2027 due to increasing Chinese supply.
- Trendforce reports that SK Hynix and Samsung Electronics plan to bring seven new memory plants online in 2028, potentially creating a capacity inflection point.
- Micron recently agreed to pay $600 million over five years to settle a patent dispute with Netlist, according to Barron's.
Background
Micron has been a focal point for AI memory investment since August 2026, when CEO Sanjay Mehrotra announced a $250 billion U.S. manufacturing build-out through 2035 to meet data-center demand exceeding current supply. In September, analysts noted that Micron's long-term take-or-pay contracts, totaling roughly $100 billion, have altered the traditional boom-bust memory cycle. However, concerns persist that new capacity from competitors and Chinese suppliers could eventually resolve the shortage, potentially tempering near-term profit margins.
How outlets are covering it
D.A. Davidson and MarketWatch emphasize Micron's undervalued status, with Luria arguing that the stock's cheap valuation multiple does not account for its multi-year growth trajectory and upcoming buybacks. Conversely, Barron's and Citi highlight cyclical risks, noting that while Micron has secured 75% of 2027 production, the market remains hesitant to assign a permanently higher price-to-earnings multiple until a downcycle is proven. Barron's points to new capacity from SK Hynix and Samsung in 2028 as a potential trigger for a price peak, while Citi's Atif Malik cites increasing Chinese supply as a factor that could drive prices down as early as mid-2027. Seeking Alpha focuses on the sheer magnitude of the price target increase, noting the 195% implied upside from current levels.
Why it matters
Micron's valuation hinges on whether AI-driven memory demand can sustain high prices beyond 2027. If long-term contracts and U.S. manufacturing investments successfully insulate the company from traditional cyclical downturns, the stock could see significant re-rating. However, if new global capacity and Chinese supply outpace demand, the current high margins could erode, leading to a sharp correction in Micron's share price and potentially impacting the broader semiconductor sector.
What to watch
Investors will watch for signs of a memory price peak, with Citi predicting a potential top in mid-2027. Micron's ability to maintain margins will depend on the execution of its $250 billion U.S. manufacturing plan and the timing of new capacity from competitors like SK Hynix and Samsung, which are set to bring seven new plants online in 2028. The resolution of the Netlist patent dispute and the impact of the upcoming buyback program will also be key metrics for near-term stock performance.
- Micron target lifted to $3000 by DA Davidson on AI memory demand (MU:NASDAQ) Seeking Alpha
- Apple Needs Chips, and “Micron Sets the Price.” Now Micron Is Making More Money than Apple Yahoo Finance
- Micron Stock Drops. Why It Needs a Memory Price Test. Barron's
- Micron: The Memory Cycle Is Approaching Its Peak (NASDAQ:MU) Seeking Alpha
- Micron’s ridiculously cheap stock could triple from here, according to this analyst’s math MarketWatch
Want the full story? Read the original reporting
Read on Seeking Alpha