
Vahe Shahinian’s 7-Year Legal Battle Over Alleged Merchant Cash Advance Fraud
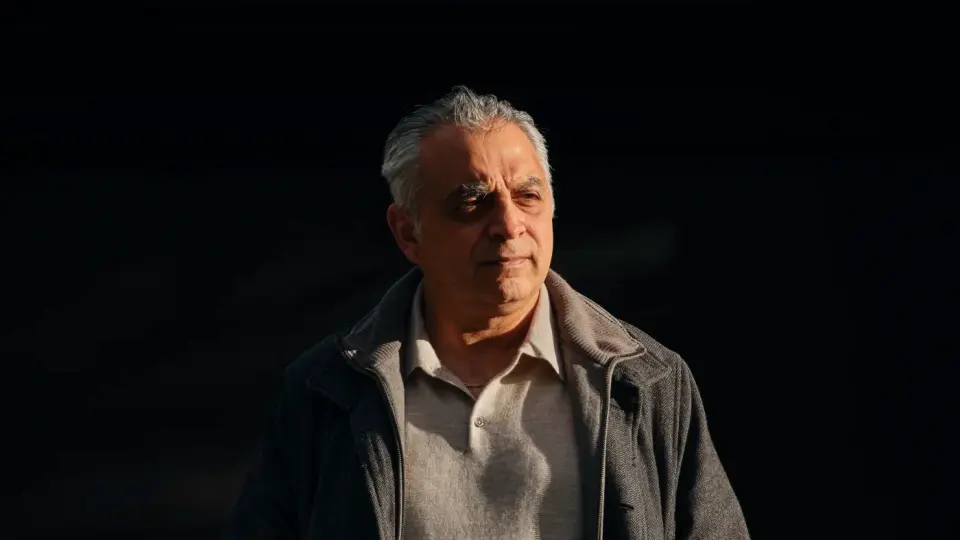
Vahe Shahinian, a Los Angeles-based event ticketing entrepreneur, is suing Wall Street firm EIN Cap for fraud after a 2019 lending deal allegedly misrepresented a merchant cash advance (MCA) as a low-interest line of credit. Despite paying daily installments for over 30 days, the promised $750,000 credit line never materialized. The dispute has spiraled into a seven-year legal battle, leaving Shahinian with an estimated $5 million in debt, including interest and fees, and resulting in the foreclosure of his home. His case, which may be the first of its kind to reach trial, highlights the risks of the largely unregulated MCA industry, where fees can exceed 200% annually. While EIN Cap denies the allegations, arguing the deal was a standard MCA arranged by brokers, Shahinian claims the structure was a 'carrot' bait-and-switch tactic targeting small business owners. The lawsuit remains pending in U.S. District Court in Los Angeles, with trial dates delayed multiple times.
Key points
- In 2019, Vahe Shahinian accepted a financing deal from EIN Cap, which he was told was a $750,000 line of credit with a 9% interest rate, requiring 30 days of $3,600 daily payments to unlock the funds.
- Shahinian alleges that the promised credit line never arrived, and the arrangement was actually a merchant cash advance (MCA), a high-cost funding method often disguised as traditional loans to trap borrowers.
- The dispute has lasted seven years, with Shahinian accruing an estimated $5 million in total debt, including approximately $3 million in interest and fees, leading to the foreclosure of his Glendale, California home.
- Shahinian’s lawyer, Shane Heskin, describes the tactic as 'carroting,' where brokers dangle attractive loan terms to secure MCA signatures, a practice he says is increasingly common among first-time borrowers and immigrants.
- EIN Cap denies fraud, stating in court filings that it only provided an MCA and that brokers made the specific promises; however, the firm’s counsel declined further comment due to the pending litigation.
- Shahinian’s case is notable as potentially the first MCA fraud lawsuit to go to trial, though the trial date has been delayed three times, most recently by nine months, while he continues to track down other victims of similar debt collection tactics.
Background
The merchant cash advance industry has grown rapidly as a primary funding source for small businesses, often filling gaps left by traditional banks and the Small Business Administration. While these products offer fast access to capital, they are largely unregulated and can carry annualized fees ranging from 25% to over 200%. Recent regulatory efforts, such as California’s new laws requiring MCA licensing and background checks starting in 2028, aim to address these issues, but many borrowers, like Shahinian, face consequences before these protections take effect. This case follows a broader trend of small business financial distress, where entrepreneurs often turn to high-cost emergency funding when traditional credit is unavailable, sometimes leading to cascading debt and bankruptcy.
Why it matters
This case illustrates the severe financial risks small business owners face when navigating the unregulated merchant cash advance industry. It highlights how deceptive marketing tactics can trap entrepreneurs in cycles of high-interest debt, potentially leading to personal bankruptcy and loss of assets. As the MCA industry continues to expand, this lawsuit may set a precedent for holding lenders accountable for misrepresenting financial products, offering potential hope for other borrowers caught in similar situations.
What to watch
Shahinian’s lawsuit against EIN Cap remains pending in U.S. District Court in Los Angeles, with the trial date delayed by nine months. The outcome will determine whether he can recoup the estimated $5 million in debt. Meanwhile, California’s new MCA regulations, including licensing and background check requirements, are set to take effect in 2028, which may impact future lending practices but will not retroactively resolve Shahinian’s case.
Want the full story? Read the original reporting
Read on NPR