
France’s Debt Crisis Deepens as Political Gridlock and Street Unrest Spike Bond Yields
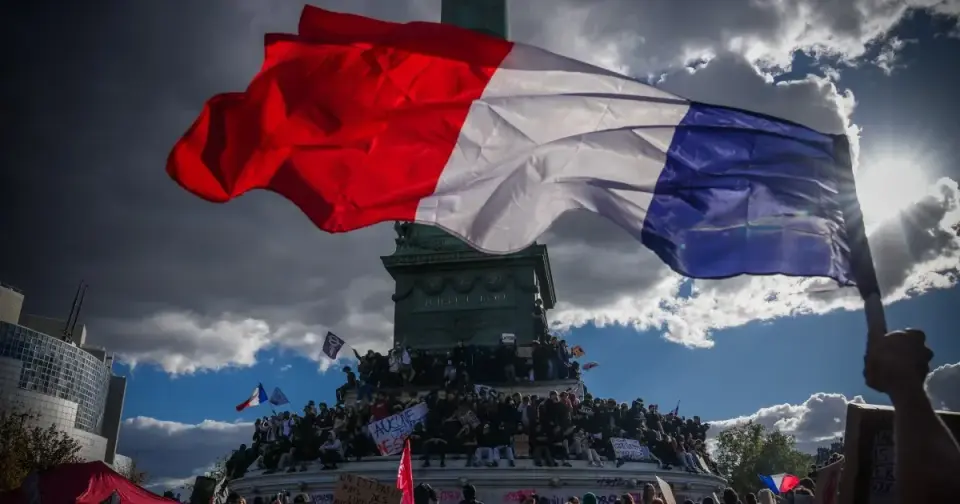
France’s 10-year bond yields have surged to nearly 5%, their highest level since 2002, as investors demand higher returns due to political instability and rising borrowing costs. The country’s national debt has reached 119% of GDP, with a projected 2026 deficit of 5.4%. Prime Minister Sébastien Lecornu faces a fragmented parliament and street protests over budget cuts, complicating efforts to restore fiscal credibility ahead of the 2027 presidential election.
Key points
- France’s 10-year bond yield has risen over 130 basis points since June, topping 4.9%.
- National debt stands at approximately 3.6 trillion euros, or 119% of GDP, the highest since WWII.
- The 2026 budget deficit is expected to reach 5.4% of GDP, far above the EU average.
- Prime Minister Lecornu is struggling to pass a 54 billion euro savings budget in a divided National Assembly.
- Street protests and riots have intensified over proposed cuts to public services and education.
Background
France’s debt-to-GDP ratio hit a record 119% by June 2026, driven by persistent deficits and rising interest costs. The government plans to borrow a record 340 billion euros in 2027 to manage refinancing. Earlier concerns highlighted that political polarization between far-left and far-right candidates had already spooked investors, raising fears of broader eurozone instability. The IMF has also shifted focus to developed nations as debt crises deepen in wealthy economies.
How outlets are covering it
Al Jazeera emphasizes the political paralysis in the National Assembly as the primary driver of market anxiety, noting that the government lacks a clear path to a sustainable budget. The New York Times frames the situation as a 'doom loop' where populist pressure from citizens conflicts with the need for fiscal austerity demanded by bond investors. Euronews highlights the contagion risk to Italy, with Oxford Economics modeling that a severe widening of France’s bond spread could trigger a recession in both France and Italy by 2027. Yahoo Finance notes that while yields dipped slightly in recent trading, they remain near 24-year highs, reflecting ongoing volatility.
Why it matters
France’s fiscal instability threatens to destabilize the broader eurozone, particularly high-debt economies like Italy. Rising borrowing costs could force further spending cuts or tax hikes, weakening economic growth and making debt harder to control. If the government fails to reassure investors before the 2027 presidential election, it risks a loss of economic credibility and potential need for ECB or IMF assistance.
What to watch
The immediate focus is on passing a credible 2027 budget that reduces the deficit to around 5% of GDP to calm markets. Investors are watching for clear legislative commitments on fiscal consolidation, particularly regarding the retirement age. The outcome of the spring 2027 presidential election, where Marine Le Pen is currently leading in polls, will be critical in determining whether France can implement the necessary reforms to restore investor confidence.
- France’s growing debt woes: How bond markets set countries’ borrowing costs Al Jazeera
- A ‘Doom Loop’ Threatens France as Populism Confronts Markets The New York Times
- French markets tumble as riots add to political crisis Reuters
- Could France’s debt troubles tip Italy into recession? Euronews.com
- French bond yields dip but remain near 24-year high in volatile trading Yahoo Finance
Want the full story? Read the original reporting
Read on Al Jazeera