
Nvidia Faces Valuation Reality Check Amid Growth Outlook
TL;DR Summary
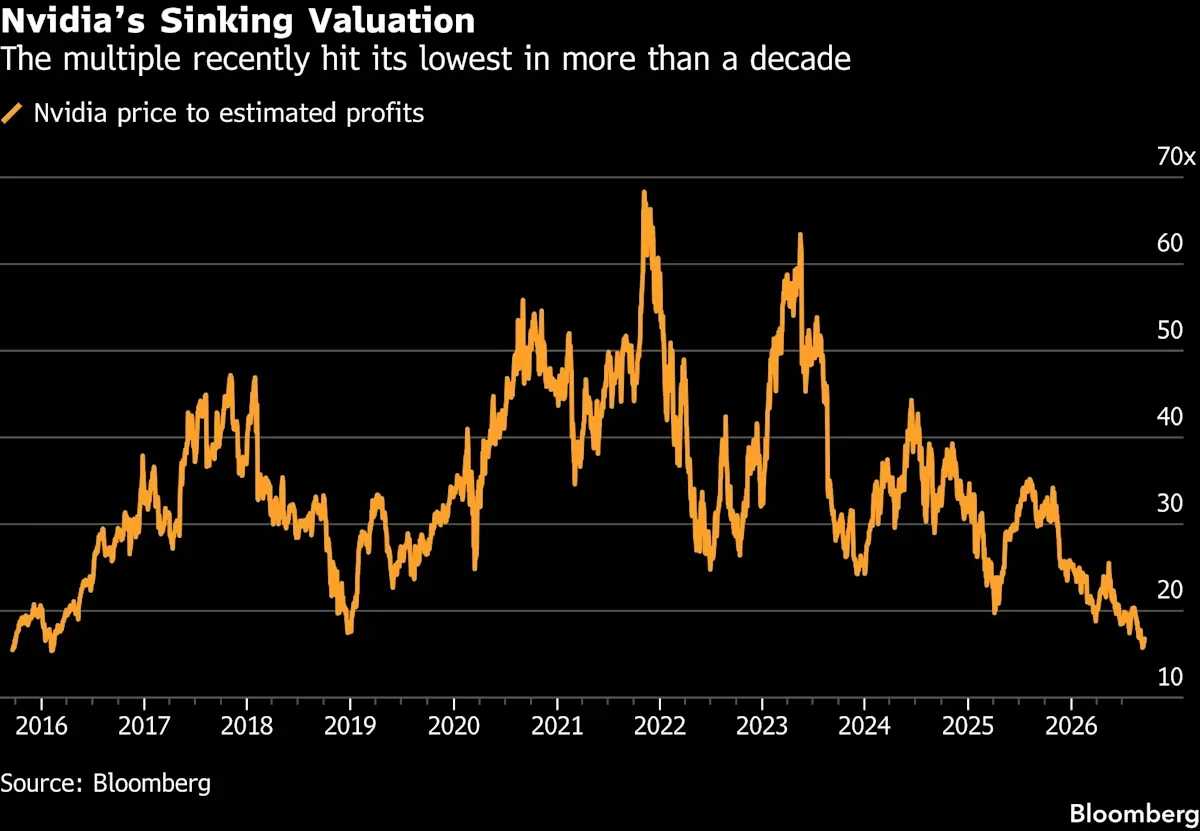
Nvidia’s stock is trading near 17x forward earnings, the cheapest in over a decade, even as its growth prospects remain strong with anticipated 2027–2028 revenue and profit gains. Analysts warn that margins may contract due to higher memory costs and increasing competition, and the market is pricing in slower AI capex growth, creating a potential multiple de-rating even as fundamentals stay robust. Some say the current price offers an attractive entry point if AI demand stays resilient.
Reading Insights
Total Reads
1
Unique Readers
8
Time Saved
25 min
vs 26 min read
Condensed
98%
5,057 → 77 words
Want the full story? Read the original article
Read on Yahoo Finance