
France's Debt Crisis Tests Eurozone Stability
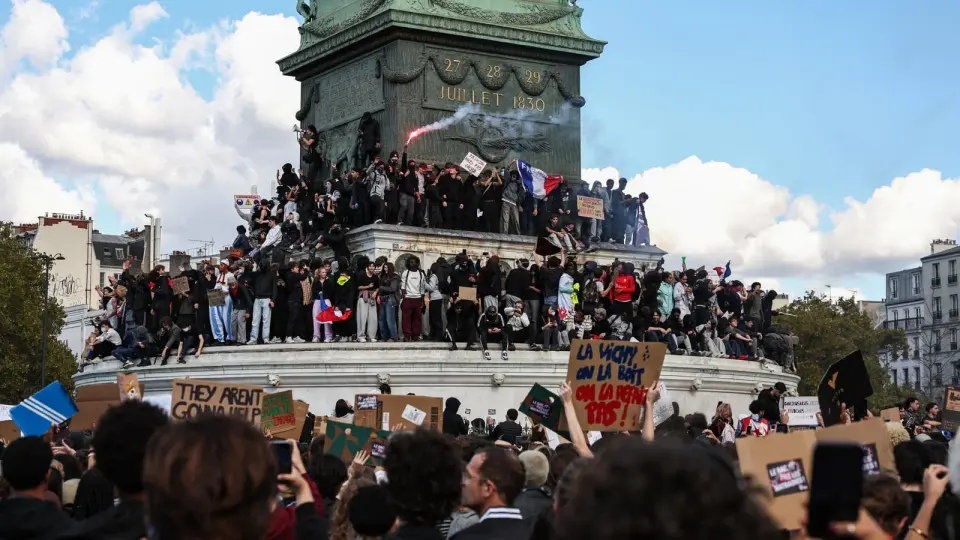
France’s 10-year bond yield surpassed 5% for the first time since 2002, widening the spread with German bonds to over 170 basis points. This surge, driven by high deficits and political instability, has raised fears of contagion across the euro zone, though experts note structural reforms may limit spillover effects.
Key points
- France’s 10-year bond yield exceeded 5%, with the spread against German bonds reaching 170 basis points, the highest since the 2010s debt crisis.
- Credit default swap costs for French government debt hit their highest levels since 2012, signaling heightened default risk.
- The European Central Bank (ECB) is expected to maintain interest rates, with officials stating that fiscal solutions must originate in France, not through monetary intervention.
- France’s debt-to-GDP ratio stands at 119%, and the government faces challenges in passing a budget with €43 billion in spending cuts due to a lack of parliamentary majority.
- Analysts warn of a potential 'doom loop' where rising debt costs exacerbate fiscal strain, but note that current eurozone banking integration reduces contagion risks compared to the 2010s.
Background
This situation follows a period of rising global debt concerns, including the AI infrastructure debt crisis reported in October 2026. France’s economic slowdown, with growth forecasts cut to 0.5%, and ongoing social unrest, including planned strikes on November 5, have intensified investor anxiety. The ECB’s recent rate hikes to 2.5% and inflation at 3.8% add to the pressure on borrowing costs across the euro zone.
How outlets are covering it
CNBC highlights the risk of fragmentation, noting that while France’s debt levels are high, they are 'known' and less likely to trigger a crisis than Greece’s hidden deficits in 2009. Euronews emphasizes the ECB’s reluctance to intervene, with Christine Lagarde stressing that fiscal solutions must come from France, and the possibility of using the Transmission Protection Instrument (TPI) as a last resort. The New York Times frames the issue as part of a broader 'populism-bond market doom loop,' linking weak government finances and investor distrust to potential systemic risks, though it does not provide specific data on contagion.
Why it matters
France’s debt crisis could trigger a broader eurozone financial instability if contagion spreads, affecting borrowing costs for other countries like Italy and Spain. The ECB’s response, or lack thereof, will be critical in determining whether the crisis remains contained to France or escalates into a systemic risk for the euro zone.
What to watch
The ECB is expected to hold rates steady at its next meeting, with a focus on fiscal policy in France. A Moody’s downgrade of France’s credit rating is anticipated, and further protests are expected on November 5. The ECB may consider using the TPI if fragmentation worsens, but for now, it is likely to pause bond holdings reduction rather than intervene directly.
- France is flashing euro crisis signals. This time, the fault lines are different CNBC
- A French Accident Waiting to Happen Bloomberg.com
- France’s Debt Crisis Deepens as Foreign Investors Look for the Exit WSJ
- Could France's bond turmoil force the ECB's hand? Euronews
- A Debt-Fueled “Doom Loop” The New York Times
Want the full story? Read the original reporting
Read on CNBC