
TSMC Posts Record Q3 Profit as AI Demand Outpaces Market Jitters
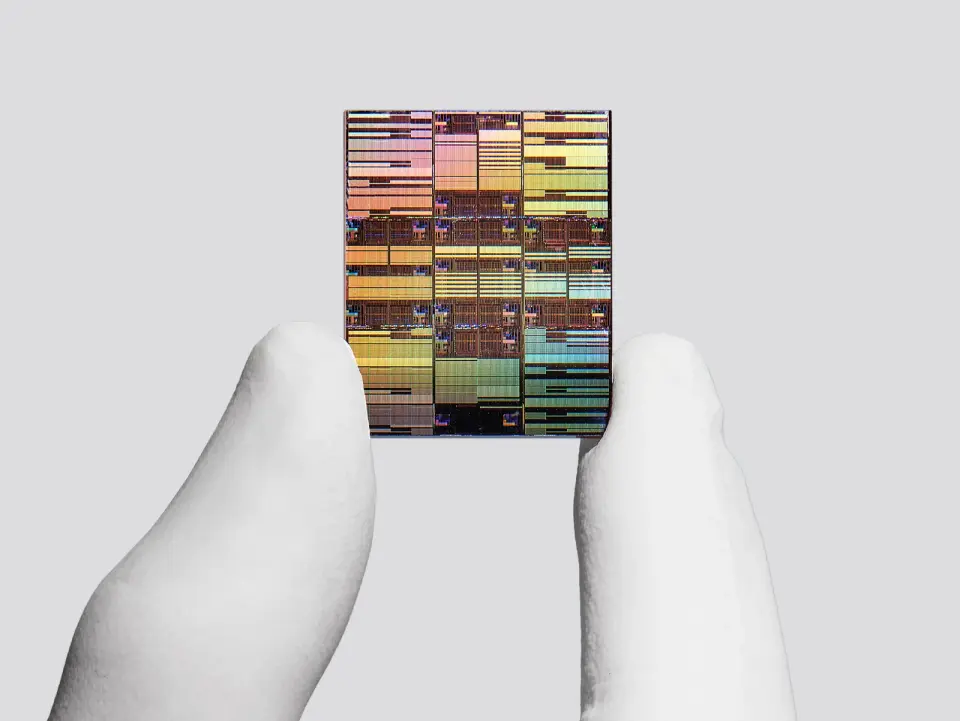
Taiwan Semiconductor Manufacturing (TSMC) reported record third-quarter net profit of NT$763.1 billion, up 68.7% year-over-year, driven by surging AI chip demand. Revenue reached $46.36 billion, beating estimates, while high-performance computing accounted for 68% of sales. Despite a recent 7.7% stock dip on AI spending fears, the company raised its full-year growth guidance to over 40% and maintains strong demand visibility through 2030.
Key points
- Net profit hit a record NT$763.1 billion, exceeding analyst expectations of NT$746.34 billion.
- Revenue totaled $46.36 billion, surpassing the consensus estimate of $44.7 billion.
- High-performance computing represented 68% of revenue, with 3-nanometer chips making up 33% of total sales.
- Management raised full-year revenue growth guidance to slightly above 40%, up from 30% earlier in the year.
- The 2026 capital expenditure budget was increased to $60-64 billion, with an additional $100 billion committed to Arizona facilities.
- Gross margin guidance for Q3 stands at 65-67%, with expected compression of 3-4 points due to the 2-nanometer production ramp.
Background
TSMC serves as the primary foundry for major AI chipmakers including NVIDIA, Apple, AMD, and Qualcomm. Recent market volatility has seen capital rotate from South Korean memory giants toward Taiwan’s advanced manufacturing sector, with the Taiex index gaining approximately 70% year-to-date. Geopolitical tensions, including delayed US arms sales to Taiwan and shifting US-China diplomatic dynamics, continue to influence investor sentiment regarding the company’s regional risk profile.
How outlets are covering it
24/7 Wall St. emphasizes the disconnect between TSMC’s accelerating revenue growth and its recent share price decline, highlighting concerns over margin compression from the 2-nanometer ramp and heavy capital expenditure. CNBC focuses on the record-breaking profitability and strong operating margins, noting that 3-nanometer chips now dominate revenue and that free cash flow surged to NT$476.56 billion. While 24/7 Wall St. flags potential demand dips and Chinese competition as risks, CNBC highlights the company’s pricing power and expansion plans, including a potential Texas facility, as evidence of sustained AI-driven momentum.
Why it matters
TSMC’s performance serves as a key indicator for the global AI hardware cycle. Its ability to maintain high margins despite new technology ramps and massive capital investments signals continued demand for advanced chips. The divergence between its strong fundamentals and recent stock volatility reflects broader market anxieties about AI spending sustainability, making its results a critical benchmark for the semiconductor sector.
What to watch
Investors will watch for fourth-quarter guidance and gross margin performance in the upcoming earnings report. Key risks include margin compression from the 2-nanometer transition and any shifts in hyperscaler capital expenditure plans. The company’s expansion in Arizona and potential entry into Texas will also be monitored for long-term supply chain resilience.
- Taiwan Semiconductor’s Top Line Growth is Starting to Raise Eyebrows 24/7 Wall St.
- TSMC posts record profit for a sixth straight quarter, beating estimates on AI boom CNBC
- TSMC’s Profit Surpasses Expectations After AI Orders Rush In Bloomberg.com
- AI Demand Extends TSMC’s Record Earnings Streak WSJ
- TSMC Q3 profit jumps 69% to record, beating expectations Reuters
Want the full story? Read the original reporting
Read on 24/7 Wall St.