
Mississippi caregiver sells home, exhausts 401(k) to cover $6,750 monthly dementia care
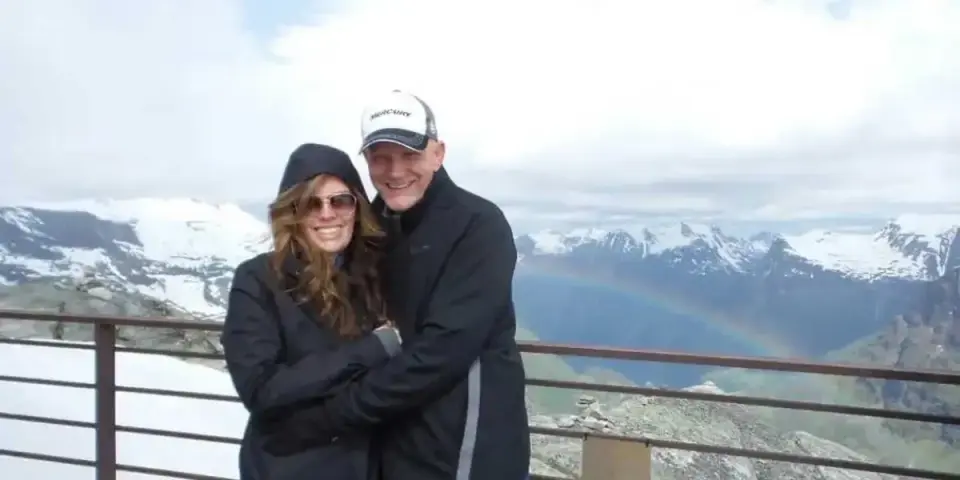
Wendy Rowland, 53, retired in her early 50s to care for her husband, who was diagnosed with early-onset Lewy body dementia. After two years in a memory care facility, she has exhausted his 401(k) and sold their 20-year-old home to cover the $6,750 monthly care cost. Her husband receives $2,700 monthly in disability benefits, which does not cover half the facility fee. Rowland now lives in a townhouse 3.5 hours away, navigating the complex financial and logistical demands of long-term care largely without professional guidance.
Key points
- Rowland’s husband, 59, has early-onset Lewy body dementia and has been in a memory care facility for over two years.
- The facility costs $6,750 monthly; his disability benefits cover only $2,700 after Medicare deductions.
- Rowland sold their 2004-built home to fund care and now pays an $800 monthly mortgage on a new townhouse.
- She returned to work after 20 years as a stay-at-home parent to help offset expenses.
- Rowland navigated the care process largely alone, citing a lack of accessible information and the need for an elder law attorney.
Background
Recent coverage highlights the growing awareness of early-onset dementia and the emotional toll on caregivers. A September 2026 article on Dr. Zaldy Tan’s new book emphasized the importance of early evaluation and the resilience required of family members. Similarly, a story about Manchester researcher Helen Beaumont detailed the diagnostic delays and marital strains associated with young-onset dementia, underscoring the systemic gaps in support for caregivers.
Why it matters
This case illustrates the severe financial strain faced by middle-aged Americans caring for spouses with early-onset dementia. The exhaustion of retirement savings and the sale of primary residences highlight the inadequacy of current disability and Medicare coverage for long-term memory care. It underscores the urgent need for better financial planning, accessible information, and support systems for caregivers in their 50s.
What to watch
Rowland faces uncertainty once the proceeds from her home sale are depleted. She is currently managing her husband’s care from a distance, relying on her granddaughter for local support. The case may prompt further discussions on the need for more accessible long-term care insurance and financial guidance for middle-aged caregivers.
Want the full story? Read the original reporting
Read on Business Insider