
Krugman Warns France Is 'Too Big to Save' Amid Bond Sell-Off and Budget Gridlock
Nobel laureate Paul Krugman argues France has crossed a threshold from 'too big to fail' to 'too big to save' due to unsustainable fiscal policies and political instability. While the European Central Bank retains tools like the Transmission Protection Instrument, former chief Jean-Claude Trichet insists France must first demonstrate credible fiscal responsibility. Allianz Trade notes that while current bond spreads are not at crisis levels, a potential Eurozone-wide contraction could trigger intervention, with the 2027 presidential election posing the next major risk.
Key points
- Paul Krugman states France is on a fiscally unsustainable path, with high debt-to-GDP ratios and large deficits, risking a crisis similar to the 2009-2012 sovereign debt crisis.
- Krugman highlights that bailing out France would be extremely expensive for the ECB and politically contentious, especially given the country's move away from fiscal responsibility.
- Former ECB chief Jean-Claude Trichet urges French politicians to find compromise and deliver a credible budget, noting that intervention tools like the TPI exist but require France to 'help itself' first.
- Allianz Trade reports that 10-year OAT yields have risen 150 basis points, driven by fiscal weakness and a 'short Europe' trade, with market depth more than 50% below normal.
- Allianz Trade projects a baseline scenario of a watered-down 2027 budget passed by year-end, but warns that adverse scenarios could lead to spreads reaching 175-200 basis points and potential Eurozone contagion.
Background
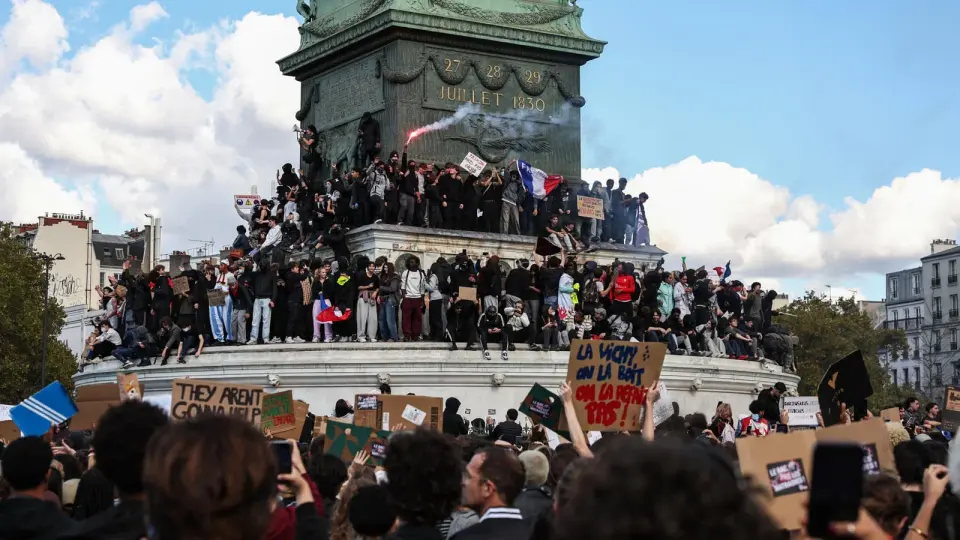
France has faced ongoing political and fiscal challenges, with student protests over education underfunding and a contentious 2027 budget. The country's debt has risen from 98% of GDP in 2019 to over 119% in Q2 2026, and fiscal deficits have remained above 5% of GDP for four consecutive years. The 2026 deficit is now expected at -5.4% against a -5% initial target.
How outlets are covering it
CNBC emphasizes the political and economic risks of a French crisis, with Krugman warning of a potential 'ugly scenario' and Trichet urging political responsibility. Allianz Trade provides a more technical analysis, noting that while current spreads are not at crisis levels, the 'short Europe' trade and political fragility are amplifying the sell-off. Allianz Trade also highlights the potential for a Eurozone-wide crisis if oil prices remain high and France's fiscal slippage continues.
Why it matters
A French debt crisis could have significant implications for the Eurozone, given France's size and importance in the European economy. The ECB's potential intervention, while possible, would be politically contentious and expensive, and the 2027 presidential election adds further uncertainty to France's fiscal trajectory.
What to watch
The French government and parliament must pass a credible 2027 budget by year-end, potentially through ordinances or Article 49.3. The 2027 presidential election, scheduled for April and May, will be the next major test of France's fiscal and political stability. The ECB may intervene if spreads reach 175-200 basis points and there is a substantial Eurozone-wide contraction.
- Nobel winner Krugman says France may have become 'too big to save' CNBC
- French Markets Are Getting the Boiling FROGS Treatment Bloomberg.com
- The ECB will sit on the sidelines during France’s debt sell-off Financial Times
- Toasted, not burnt France s bond sell-off and the road to the 2027 election Allianz Trade
- European Central Bank: Conditional support and French risks – Rabobank FXStreet
Want the full story? Read the original reporting
Read on CNBC