
Fed Raises Rates as Borrowers Brace for Higher Costs and Savers May Benefit
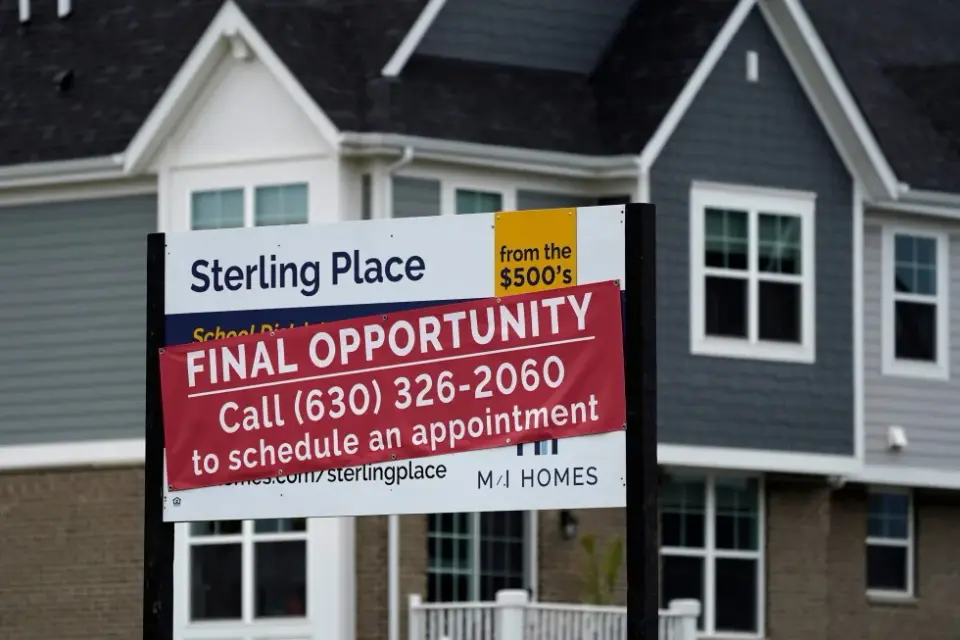
The Federal Reserve’s rate increase is poised to lift borrowing costs for households while potentially boosting savers’ yields; even as mortgage rates could rise, many homeowners remain protected by recently locked-in low rates, with roughly half of outstanding mortgages at 4% or lower and about 20% at 3% or lower in early 2026. The housing market has cooled as existing-home sales slow, and credit-card rates—tied to the prime rate—are expected to climb in the coming months, helped by higher rates, while auto loan costs remain elevated. Overall, Americans face higher borrowing costs amid persistent high living costs, even as some lenders note many households are still managing comparatively well.
- Fed rate hike likely means more expensive credit cards and mortgages, but savers may rejoice apnews.com
- Fed raises interest rates for the first time since 2023 CNN
- Fed Issues First Rate Hike Since 2023 wsj.com
- Live Updates: Warsh and Fed Officials Raise Interest Rates to Fight Inflation The New York Times
- Federal Reserve hikes key rate for 1st time in 3 years, defying Trump demands for a cut apnews.com
Want the full story? Read the original reporting
Read on apnews.com