Tag

Mortgages

All articles tagged with #mortgages

RBA hikes rates to 15-year high as global bond rout forces Australia’s hand
economy8 hours ago

RBA hikes rates to 15-year high as global bond rout forces Australia’s hand

The Reserve Bank of Australia (RBA) raised the cash rate by 25 basis points to 4.6% on September 29, 2026, marking the fourth hike of the year and the highest level since November 2011. The decision was driven by persistent inflation, capacity constraints, and a global surge in bond yields. Unlike previous hikes, this move will directly increase monthly mortgage repayments for almost all borrowers, as most had not reduced payments during the 2025 rate cuts. While the RBA cited the Middle East conflict and AI-driven demand, critics argue government spending is a primary driver. The move adds approximately $114 to monthly repayments on a $750,000 loan, with further hikes priced in by markets.
UK First-Time Buyers Face £17k Barrier as Government Plans LISA Overhaul
economy1 day ago

UK First-Time Buyers Face £17k Barrier as Government Plans LISA Overhaul

Saving for a UK home deposit requires approximately £17,000, covering a 5% deposit on the average £272,000 house price plus legal fees. While the new 'Your First Home' scheme aims to lower this barrier, experts suggest four strategies: treating savings like a bill, using Lifetime ISAs (LISAs), starting early to leverage compound interest, or seeking low-deposit mortgages. The government is also consulting on replacing the LISA with a simpler First Time Buyer ISA to remove withdrawal penalties.

Starter-home energy bills can surprise first-time buyers
real-estate8 days ago

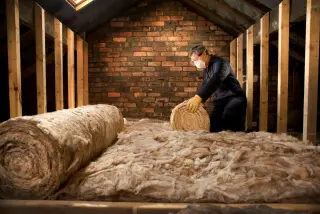
Starter-home energy bills can surprise first-time buyers

First-time buyers should budget for utility costs beyond the mortgage, as national average monthly bills rose to $412 in 2025 (a 7% increase from 2024). The Washington Post article urges buyers to factor energy costs into their housing budget and to consider cost-saving steps, such as insulating attics and pursuing energy-efficiency improvements, to avoid sticker shock after purchase.

Fed hikes rates again after long pause to curb persistent inflation
economy12 days ago

Fed hikes rates again after long pause to curb persistent inflation

Fed raises the federal funds rate by 0.25 percentage points to 3.75-4% in a unanimous vote, the first hike in more than three years, citing inflation that remains above target. Officials expect further increases to about 4-4.25% by year‑end and 4.25-4.5% next year, with cuts not expected until 2028-2029. The higher rates will lift borrowing costs for loans, mortgages, and credit cards, though could boost savers; banks lifted their prime rates in response, amid political backlash and concerns about higher debt for Americans.

Fed Rate Hike Signals Subtle Shifts in Mortgage, Auto Loans and Card Rates
economy12 days ago

Fed Rate Hike Signals Subtle Shifts in Mortgage, Auto Loans and Card Rates

The Federal Reserve’s first rate increase since 2023 isn’t an immediate spike for mortgage or auto loan rates; you’ll likely see gradual moves as Treasury yields influence borrowing costs, with car loan and credit card rates edging higher over time while mortgage rates adjust more slowly and savings yields may rise.

Fed Raises Rates as Borrowers Brace for Higher Costs and Savers May Benefit
business12 days ago

Fed Raises Rates as Borrowers Brace for Higher Costs and Savers May Benefit

The Federal Reserve’s rate increase is poised to lift borrowing costs for households while potentially boosting savers’ yields; even as mortgage rates could rise, many homeowners remain protected by recently locked-in low rates, with roughly half of outstanding mortgages at 4% or lower and about 20% at 3% or lower in early 2026. The housing market has cooled as existing-home sales slow, and credit-card rates—tied to the prime rate—are expected to climb in the coming months, helped by higher rates, while auto loan costs remain elevated. Overall, Americans face higher borrowing costs amid persistent high living costs, even as some lenders note many households are still managing comparatively well.

Mortgage underwriting expands to include VantageScore 4.0 alongside FICO
business13 days ago

Mortgage underwriting expands to include VantageScore 4.0 alongside FICO

Fannie Mae and Freddie Mac will allow VantageScore 4.0 to be used alongside classic FICO in mortgage underwriting, potentially helping borrowers with thin credit histories by incorporating rent and other data. FHA will insure loans underwritten with VantageScore 4.0 and FICO 10T starting Jan 1, and FHFA is weighing reducing credit reports to two or even a single report, though lenders currently rely on tri-merge; experts say alternative data could improve eligibility and pricing, while rent-reporting remains uneven.

Rising rates push borrowers toward adjustable-rate mortgages
business19 days ago

Rising rates push borrowers toward adjustable-rate mortgages

Mortgage rates climbed again last week, nudging borrowers toward riskier adjustable-rate mortgages (ARMs), which accounted for 8.5% of applications—the highest since June. The 30-year fixed rate rose to 6.85% from 6.79%, while the five-year ARM fell to 5.82% from 5.94%. Overall application volume dropped 2.7%, with refinances down 6% and purchases essentially flat, though year-over-year activity remains higher. Investors await inflation data that could move rates in either direction.

Why paying off a low-rate mortgage early may cost you more
business24 days ago

Why paying off a low-rate mortgage early may cost you more

Rocket Mortgage analyzed nearly 3 million loans across all 50 states over the past five years and found that about 25% of homeowners pay off or prepay their mortgage faster than required, including some with very low rates. Financial planners generally advise keeping low-rate debt and investing elsewhere for growth, though some borrowers do it for peace of mind. The article argues the biggest potential benefits of early payoff would go to people who are least likely to choose that path, highlighting a misalignment between who benefits and who pre-pays.

Rates surge to a 14-month high as bond selloff persists and Fed signals potential hikes
mortgages25 days ago

Rates surge to a 14-month high as bond selloff persists and Fed signals potential hikes

Mortgage rates rose to their highest level in over a year as a global bond selloff intensified and a Fed speech suggested higher rates could be needed. Freddie Mac puts the 30-year fixed at 6.71% for the week, with purchase rates today roughly 6.69% for a 30-year loan and 6.00% for a 15-year loan (plus mid‑6% ARMs and similar VA figures). Refinance rates are also up, about 6.68% for a 30-year and 6.09% for a 15-year loan. Traders assign roughly a 50/50 chance of a 25‑basis-point Fed hike at the mid‑September meeting. The article explains what drives rate moves, how to compare lenders, and why rates differ between purchase and refinance loans, while noting refinancing can be worthwhile if you can lock in a rate meaningfully lower than your current mortgage and outlining general mortgage basics.

UK Millennials Face a Long Climb Onto the Housing Ladder
uk-economy1 month ago

UK Millennials Face a Long Climb Onto the Housing Ladder

Millennials in the UK still have far lower odds of owning a home than previous generations; decades of house price growth outpacing incomes and a long-term housing shortfall driven by high construction costs, planning barriers, and labor shortages have kept deposits high and rents consuming a large share of income. While recent price growth has slowed and some lenders are offering larger loans with smaller deposits, meaningful relief requires years of higher housing supply and planning reforms.

How a $40 Trillion U.S. Debt Could Lift Your Mortgage and Loan Costs
economy1 month ago

How a $40 Trillion U.S. Debt Could Lift Your Mortgage and Loan Costs

The U.S. national debt has topped $40 trillion, and rising borrowing costs could push mortgage rates and other loan costs higher as Treasury yields climb. Larger interest payments threaten fiscal room for priorities and could feed inflation if the debt is monetized; with deficits driven by tax-and-spending policy, economists say the path forward requires slower spending growth and higher revenue, though political stalemate persists.

Debt surge could hit family budgets, student loans, and retirees
national1 month ago

Debt surge could hit family budgets, student loans, and retirees

With the national debt nearing $40 trillion, economists warn persistent deficits will raise borrowing costs and affect everyday finances: higher student-loan payments, pricier mortgages, and potential Social Security cuts unless policy changes occur. The Conference Board’s analysis notes a 2028 incoming student with a $45,000 loan could owe about $279,000 (or roughly $466,000 in extreme rate conditions); a $600,000 home with 20% down could total around $2.89 million (rising to about $3.64 million in a shock scenario); and Social Security insolvency could occur by 2032 unless taxes rise or deficits shrink. Small-business lending would also face higher costs, and lawmakers have largely stalled on decisive action.

Markets rally as inflation cools and rate-hike bets ease
business1 month ago

Markets rally as inflation cools and rate-hike bets ease

Stocks rose and bond yields fell after July's producer price index showed inflation broadly flat and energy pressures easing, fueling expectations that the Fed may pause rate hikes this year. The S&P 500 and Nasdaq advanced, the 10-year yield slipped to about 4.61% before rebounding, and mortgage rates edged lower to around 6.69%. Some Fed officials signaled a push to rise rates to bring inflation down, with the next policy decision due in September.