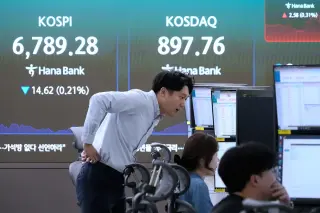
U.S. stock futures trade mixed ahead of major bank earnings, as Asian markets plunge on oil spikes and memory chip weakness. Investors await Q3 results from JPMorgan, Goldman Sachs, and others, with S&P 500 profit growth expected to reach 30%.
U.S. stock markets are currently digesting recent oil price fluctuations, with investor attention shifting toward the upcoming third-quarter earnings season. While energy costs have recently caused volatility, the broader market is looking to corporate financial results for the next directional cue.
US stock futures opened flat Monday after a winning week, with investors focusing on Q3 earnings and inflation data. Major banks report this week amid rising oil prices and bond yields, while Trump considers joining Saudi strikes against Houthis in Yemen.
Q3 earnings season begins Tuesday with major banks reporting, amid concerns over soaring yields and a potential Federal Reserve rate hike. The September CPI report on Wednesday is critical for determining October monetary policy, while telecom stocks fell after SpaceX acquired spectrum licenses.
U.S. stock markets ended a volatile week with gains on Friday, October 9, 2026, as investors looked ahead to the start of the third-quarter earnings season. The Dow Jones Industrial Average rose 0.83%, the S&P 500 gained 0.59%, and the Nasdaq Composite climbed 0.64%. The rally was supported by easing oil prices and a rebound in technology stocks after a brief AI-related selloff. Consumer confidence fell to a five-month low due to high fuel costs, but President Trump announced a deal for Russia to supply diesel to the U.S. and global markets, which helped calm energy markets. The week marked the 11th bull market since the 1950s, which is on track to become the seventh to last at least four years.
U.S. tech stocks declined Thursday afternoon as investors navigated elevated Treasury yields and oil prices. The S&P 500 and Nasdaq Composite rose slightly on Friday, but chipmakers slipped after OpenAI reported revenue significantly below earlier estimates. Analysts warn that narrow market participation in large tech names could trigger a broader pullback if earnings disappoint.
CNBC reports that the 'Magnificent Seven' tech giants may lag behind the broader stock market during the upcoming earnings season. While tech stocks have driven recent record highs, analysts suggest other sectors could outperform as investors look for value beyond the dominant AI and semiconductor leaders.
The Nasdaq Composite closed at a record high on October 7, 2026, driven by investor focus on upcoming corporate earnings. The rally was led by technology and semiconductor stocks, with Advanced Micro Devices (AMD) and Marvell Technology (MRVL) posting significant gains. While the broader market showed strength, some hard drive manufacturers like Seagate (STX) declined. This continues a recent trend of record highs for the Nasdaq, despite earlier concerns about bond yields and geopolitical risks.
U.S. stock futures indicated a flat opening on October 12, 2026, following a significant rally the previous day. The pause in momentum occurred as crude oil prices rose, reversing a recent decline, while investors awaited corporate earnings and upcoming diplomatic meetings regarding the Iran conflict. The Federal Reserve had recently raised interest rates for the first time since 2023, a move that markets had largely anticipated.
US stock futures fell on Tuesday as rising US-Iran tensions revived inflation concerns, with Dow futures flat, S&P 500 down about 0.5%, and Nasdaq futures down around 1%. Brent crude neared $91 and WTI around $84 as oil prices climbed, while the US Strategic Petroleum Reserve dropped to its lowest level since 1982. Bond yields rose globally (10-year ~4.72%, 30-year ~5.31%), even as earnings from Home Depot and Toll Brothers offer some support ahead of a busy reporting week (KLAR).
Despite a near-record run in the stock market fueled by a strong earnings season (EPS beat rates around 86%, the best since 2021), BTIG strategist Jonathan Krinsky warns that midterm-election years historically bring a meaningful pullback in August–October (about 7% or more in several past instances). With the S&P 500 benefiting from robust Q2 results, investors should consider trimming risk or hedging broad equity exposure as this historically difficult period approaches.
Global shares were mixed ahead of a retailer‑heavy week, as investors await earnings from major chains and data on the consumer mood amid inflation and rate expectations, watching how Walmart, Lowe’s and other retailers guide expectations for demand and profits.
U.S. stocks opened the week lower as oil prices climbed and Nvidia slid after reports that AI-infrastructure financing could reach roughly $500 billion, dragging the tech sector down while the broader indices dipped: the S&P 500 around -0.1%, the Dow about -0.1%, and the Nasdaq around -0.3%. Oil benchmarks surged with Brent near $85+ and WTI above $80 amid Iran-Hormuz tension and wait for CPI data that could influence Fed policy. Intel also fell after announcing a $15 billion stock offering. Earnings season continues with AI infrastructure players on the docket, as investors weigh inflation signals and rate paths.
Live earnings updates show Marriott International (MAR) down about 5.5% mid-morning as Middle East headwinds weigh the stock, while Bitcoin (BTC-USD) swings to a loss on news tied to a Trump brothers‑backed project. Palantir Technologies (PLTR) edges higher, and the broader earnings season remains a market engine with Tyson, Marriott, and ON Semiconductor among the reports this week. FactSet data suggest second‑quarter S&P 500 earnings are up roughly 47.5% year over year, well above long‑term averages, signaling robust profit growth for another quarter.
Chip and memory stocks led a broad sell-off that pushed the Nasdaq-100 briefly into correction territory (about a 10% drop from its high) as Sandisk, Western Digital, Seagate, Micron and AMD fell roughly 10% and Dell slid ~13%; Samsung Electronics and SK Hynix retreated more than 15% in Asia, with equipment makers like ASML down after a report—unverified—that a Chinese state-backed firm began mass-producing domestic chip tools. The move occurs ahead of key earnings reports from Meta, Amazon and Microsoft and amid ongoing AI-related capex, with JPMorgan forecasting AI spending near $870 billion by 2026. Apple rose, helping buoy large indices as the broader market remained resilient.