Tag

Price Target

All articles tagged with #price target

Micron Bulls See 110% Upside as AI Memory Demand Tightens
finance17 days ago

Micron Bulls See 110% Upside as AI Memory Demand Tightens

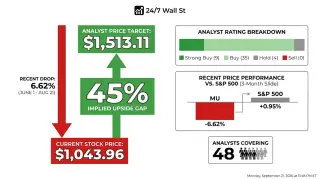
Micron Technology (MU) is trading around 7x forward earnings, but a bull case from Melius sees roughly 110% upside to $2,200 driven by long-term, contracted AI/cloud demand for high-bandwidth memory (HBM) and 16 Strategic Customer Agreements totaling about $100 billion in minimum contracted revenue with deposits. The article notes MU’s bull thesis hinges on HBM capacity remaining sold out through multi-year horizons and margins staying above prior peaks, even as the broader memory space faces potential cycle overshoot. MU is covered by dozens of analysts (about 48), with a consensus target around $1.5k, while peers Western Digital and Seagate show lower implied upside. The bull case requires belief that the AI memory cycle sustains demand beyond 2027, and risks include price moderation and capex-driven volatility in memory pricing.
Burry Bets on Lululemon Dip After Weak Q2 Results
finance1 month ago

Burry Bets on Lululemon Dip After Weak Q2 Results

Michael Burry still holds about 17% of Lululemon (LULU) and says he could add to the position if the stock sinks below $100, following a fiscal Q2 miss and reduced full-year guidance that sent LULU lower. He described the company as a “trickster” but noted he often adds to positions on declines or exits them, with his GuruFocus-linked stake highlighting the emphasis. The earnings setback is blamed on weaker China demand and rising U.S. competition, while interim co-CEO Meghan Frank says management is focusing on product development, higher marketing investment and expense control to restore growth.

Microsoft Could Hit $1,000 by 2031 If AI Growth Keeps Accelerating
investing1 month ago

Microsoft Could Hit $1,000 by 2031 If AI Growth Keeps Accelerating

Microsoft posted a record $331 billion in annual revenue with Azure topping $100 billion, yet the stock has been mostly flat. The piece outlines a scenario where MSFT could reach $1,000 by August 2031 if Azure sustains 30%+ growth, Copilot scales beyond 30 million paid seats, and capital expenditures normalize. Consensus price targets sit around $569.45, while its model shows a base of $609.58 with bull and bear cases of $709.58 and $520.81 respectively; achieving $1,000 would require about 95% upside or a large multiple expansion tied to earnings growth. Risks include AI demand slowdown and potential overcapacity from AI infrastructure spending. It’s a long-range, sponsor-linked analysis from 24/7 Wall St.

Bloom Energy’s potential 2027 upside: $5,000 could grow to about $6.8K
finance1 month ago

Bloom Energy’s potential 2027 upside: $5,000 could grow to about $6.8K

Bloom Energy (BE) is about 38% below its 52‑week high as of Aug. 25, 2026. Using that date’s close of $217.45 and a median target of $295 from 33 analysts tracked by CNN, a $5,000 investment would buy just under 23 shares and could be worth roughly $6,782 by August 2027 if BE hits the target, a ~36% gain. The Motley Fool notes price targets aren’t guarantees, even though Bloom posted over $1 billion in Q2 2026 revenue and has a meaningful role in AI-era power needs; it also cautions that monster gains aren’t guaranteed and suggests tempered expectations for BE as a long‑term, high‑risk hold for aggressive investors.

Morgan Stanley Lifts Marvell Target on Strong Data-Center Outlook
finance1 month ago

Morgan Stanley Lifts Marvell Target on Strong Data-Center Outlook

Morgan Stanley raised its Marvell Technology price target to $246 from $224 and kept an Equalweight rating after Marvell reported record Q2 revenue of $2.74 billion (up 37% YoY) and guided Q3 revenue around $3.15 billion with gross margin between 57.5% and 58.5%. The bank credited Marvell’s expanding exposure to AI data-center spending, highlighting XPU attach, optical connectivity and scale-up opportunities, and lifted its calendar 2027 data-center growth forecast to about 60% from 50%. While fundamentals are accelerating, valuation remains a concern, making the Oct. 6 Investor Day a key upcoming catalyst.

CoreWeave Backlog Signals Potential for a 2x Move by 2027
business1 month ago

CoreWeave Backlog Signals Potential for a 2x Move by 2027

24/7 Wall St. projects CoreWeave (CRWV) to reach about $166.75–$171 by Aug 2027, implying up to ~90% upside based on a $104 billion backlog that dwarfs its sub‑$50 billion market cap. The bull case hinges on improving operating margins in the low teens by Q4 and a ramp in power/inference monetization, but the stock carries heavy cash burn (free cash flow −$5.7B in Q2) and large capex guidance ($35–$39B for 2026). Comparisons to Nebius and Oracle are used, while a bear case warns of financing/interest risks; sentiment is mixed and one noted NVIDIA caller did not include CRWV among top AI stocks.

Bank of America Sees 50% Upside for Micron on AI-Driven Memory Demand
finance1 month ago

Bank of America Sees 50% Upside for Micron on AI-Driven Memory Demand

Bank of America reiterates a Buy on Micron and lifts its price target to $1,550, signaling about 50% upside as AI-driven memory demand and disciplined supply could lift 2030 earnings to roughly $200–$250 per share with margins above 80%. The bull case hinges on strong demand and supply discipline seen in Sandisk’s investor day, but the analyst warns the memory cycle could stay cyclical if supply outruns demand, and MU’s valuation carries signs of caution.

Broadcom’s AI Push Fires Upward Bets Even as Shares Slip
markets1 month ago

Broadcom’s AI Push Fires Upward Bets Even as Shares Slip

Broadcom has fallen over three months despite a strong second quarter beat and a surge in AI-related revenue. BNP Paribas Exane raised its target to $675 (about 61% upside), while the consensus target sits near $528 (roughly 26% upside) with most analysts Buy-rated. Broadcom reported Q2 revenue of $22.19B (up 47.9% YoY) and AI revenue of $10.8B, guiding Q3 AI revenue to about $16B and projecting over $100B in AI revenue by 2027. The stock trades around $418 with a forward P/E near 69. The bull case depends on AI backlog conversion and continued hyperscaler demand, while bears warn of valuation risk and customer concentration; the relative setup shows Broadcom lags peers like NVIDIA and AMD but offers meaningful upside if AI demand accelerates.

Palantir Rally Accelerates as Bank of America Signals Large Upside
finance2 months ago

Palantir Rally Accelerates as Bank of America Signals Large Upside

Palantir Technologies (PLTR) stock jumped about 9% after strong Q2 results, helped by short-covering and broader tech strength. Bank of America reiterated a Buy rating and raised its price target to 255, implying roughly 50% upside from recent levels, citing Palantir’s AI strategy, expanding US commercial contracts, and strong government relationships as key drivers of competitive advantage and future growth.

Microsoft Eyes More Upside After Azure-Driven Rally
business2 months ago

Microsoft Eyes More Upside After Azure-Driven Rally

Microsoft jumped about 25% after blowout Q4 FY26 results, led by Azure crossing $100B in annual revenue and Copilot monetization. 24/7 Wall St. assigns a $573.79 price target (roughly 23% upside over the next year) with a bull case near $603.61 and longer‑term projections, while noting capex/free cash flow risks and MSFT’s cloud advantage versus peers; the piece suggests gradual buying on pullbacks rather than chasing the rally.

Micron Buckles in July, but AI Memory Demand Sparks 85% Upside Outlook
markets2 months ago

Micron Buckles in July, but AI Memory Demand Sparks 85% Upside Outlook

MU plunged about 29% in July—the worst month in 11 years—amid broader memory-stock volatility, but analysts argue AI-driven demand should keep memory pricing elevated for the next couple of years. Morningstar lifted its MU price target to $850 from $455 on stronger upcycle expectations, and the consensus target sits around $1,522.26 implying roughly 85% upside from Friday’s close. Sentiment remains bullish despite the premarket weakness, with investors awaiting upcoming SanDisk/Western Digital results for more memory-cycle cues.

Analyst Sees Netflix Doubling Stock on Advertising Upside
business2 months ago

Analyst Sees Netflix Doubling Stock on Advertising Upside

Netflix has fallen about 44–45% over the last year and trades around $67.60, but a bull case from BMO puts a $135 target on the shares, implying roughly 100% upside if its ad revenue grows toward $3 billion by 2026 and the company continues its robust buybacks. The analysis highlights ads-driven growth as the key catalyst, while noting the stock still trades in line with the broader market’s multiple, with a consensus target near $97.91 and no sell ratings among the 50 covering analysts. The takeaway: the pullback may be an overreaction if Netflix’s ad and free cash flow trajectory materializes.”,

TD Cowen Keeps Buy on Micron, Sets $1,600 Target for 63% Upside
markets3 months ago

TD Cowen Keeps Buy on Micron, Sets $1,600 Target for 63% Upside

TD Cowen reiterates a Buy on Micron (MU) with a $1,600 price target, implying about 63% upside from the current price as supply constraints persist and demand for DRAM/HBM/NAND remains strong, aided by Supply Constrainment Agreements that boost revenue visibility. The AI-memory boom and tight DRAM markets underpin potential pricing gains, while Micron’s Q3 revenue reached $41.46B with Q4 guidance near $50B, alongside a long-term US investment plan of $250B through 2035 to expand domestic DRAM capacity.

Amazon Stock Set for Upside on AWS AI Push, Targets $324
business3 months ago

Amazon Stock Set for Upside on AWS AI Push, Targets $324

24/7 Wall St. says Amazon (AMZN) could reach about $324 by year’s end, implying roughly 31–32% upside from the current price as AWS AI monetization accelerates. The bull case hinges on AWS growth reaccelerating (AWS backlog at $364B; Trainium commitments over $225B; Anthropic deal) with a strong Q1 showing, while acknowledging free cash flow collapsing ~95% due to heavy capex (2026 capex near $200B) and rising debt. Long‑term upside is contingent on AI infrastructure execution, with projections extending beyond 2026 if ROI meets expectations and AI monetization scales, but risks include capex volatility and debt load.

SanDisk Rally Signals Risk: 27% Downside Ahead
markets3 months ago

SanDisk Rally Signals Risk: 27% Downside Ahead

SanDisk has surged ~4,800% in the past year on an AI memory cycle, but 24/7 Wall St.'s price target of $1,704.60 implies ~27% downside from current levels, with a bear case near $1,204. The note cites a sky‑high RSI near 99, lofty valuation, and reliance on multi-year contracted revenue; bulls see potential upside if those contracts hold, but the risk/reward is unfavorable at current prices, leading to a SELL recommendation with 90% model confidence.