August PPI rose 5.4% year-over-year (0.4% month), sending Polymarket odds of a 25bp Fed hike on Sept. 16 up to 61% and flipping the base case to a hike; energy prices and upstream inflation keep pressure in the pipeline as traders await CPI data and watch an elevated front-end yield curve.
US wholesale prices rose in August as energy costs climbed, with the producer price index signaling ongoing inflation pressure ahead of Friday’s CPI release. Increases were seen in sectors like airfares and hospital/physician services, reinforcing expectations that the Fed may hike rates later this year, though the upcoming CPI data will be pivotal in guiding policy.
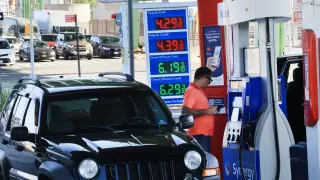
U.S. producer prices rose 5.4% year over year in August and 0.4% month over month, with goods up 1.1% and energy surging 4.2% as Brent crude topped $105, signaling persistent inflation pressures and raising odds of a Federal Reserve rate increase before year-end; core PPI rose 4.6% YoY, and investors await Friday’s CPI data, which economists expect to show a slower annual rise but a 0.4% monthly gain, as electronics costs also rose.
U.S. producer prices rose 0.4% in August, in line with economists’ expectations, with the core PPI up 0.2% as food and energy were excluded. Year-over-year PPI climbed 5.4% and core PPI 4.6%. The data precede Friday’s CPI report, which analysts expect to show a monthly uptick but again a similar year-over-year pace, keeping scrutiny on inflation. Markets are pricing roughly a 64% chance of a Fed rate hike in September and about 90% by December, aided by hawkish signals from Fed officials.
U.S. producer prices rose 0.4% in August, lifting the annual PPI to 5.4% and driven by a 4.2% jump in energy (diesel up 24.1%), while core PPI rose 0.2%; the data keeps inflation in focus ahead of the Federal Reserve's policy decision, with futures lower and yields higher as markets price higher energy and goods costs.
China’s August inflation rebounded as producer prices rose 3.8% year-on-year (vs a 3.6% forecast) and consumer prices gained 0.8% y/y, driven by energy costs, base effects, and solid high-tech demand, but underlying domestic demand remains soft with services muted and consumer goods prices slipping. Core CPI rose 1.0%, while electronics prices climbed on memory-chip shortages. Analysts say the pickup reflects weak demand and overcapacity rather than a durable upturn, and PPI could ease toward deflation next year if energy flows normalize. Weak July retail sales and urban investment, plus youth urban unemployment at 17.9%, keep Beijing under pressure and some forecasters trimming 2026 growth.
Investors are bracing for next week’s inflation readings (PPI on Thursday and CPI on Sept. 11) to judge whether the Fed will hike rates at its Sept. 15–16 meeting. Economists expect August CPI to rise about 0.4% with a 0.2% core gain, though cooling in June–July has kept the debate alive. A hotter print could lift rate-hike odds and push yields higher, while a cooler print could reinforce expectations that rates stay unchanged. The market has risen in 2026 but remains sensitive to inflation data and policy signals.
U.S. stocks advanced modestly as cooler inflation data tempered bets on aggressive Fed rate hikes: the S&P 500 rose about 0.5% and the Nasdaq roughly 0.7%, while the Dow slipped around 0.1%. July producer prices rose less than expected, echoing a cooling CPI, which renewed hopes for slower tightening this year though policymakers remain divided and investors still price in at least one rate hike by year-end. Cisco and Cerebras fell after earnings, Applied Materials is due after the close, and initial jobless claims edged higher to 209,000 while continuing claims declined. Oil prices also eased amid shifting dynamics around the Strait of Hormuz as markets awaited further earnings data.
US producer prices rose 4.7% year over year in July, down from 5.5% in June and topping economists' 4.9% forecast; core PPI rose 0.2% in July to 4.2%, the lowest in four months, while energy prices have cooled after earlier spikes driven by geopolitical tensions, signaling easing but still-elevated wholesale price pressures.
The producer price index was unchanged in July, below the expected 0.2% gain, while core PPI rose 0.2% (forecast 0.3%). Goods fell 0.7% as energy slid 3.1% (gasoline -5.7%), and services rose 0.2% led by portfolio management; annual PPI gains were 4.7% (all items) and 4.2% (core). Markets rose modestly with futures up and yields down as Fed rate-hike odds shifted, trimming the chance of a September move but keeping October/December in play. CPI rose 0.1% in July, with 0.2% core CPI; initial jobless claims rose to 209,000 for the week ended Aug. 8.
Two big tests shape the week: inflation data (CPI on Wednesday and PPI on Thursday) to gauge pricing pressure and Fed policy paths, and AI-infrastructure bellwethers Nebius NBIS, CoreWeave CRWV, and Cerebras CBRS to gauge AI capex momentum. With CAVA Group and Applied Materials reporting and ongoing questions about Fed independence amid rising yields, markets will swing on any inflation surprise or stronger AI spending signals.
China's July CPI rose 0.5% year-on-year, the slowest pace since January, helped by slower gasoline-price gains, while producer prices climbed 3.5% YoY, easing from 4.1%. Month-on-month, CPI fell 0.1%. Domestic demand remains weak as PMIs show softer momentum and retail sales edged up 1% in June after May decline, with fixed-asset investment down 5.7% in H1. GDP growth in Q2 was 4.3%, below the official target. Exports jumped about 24% in July, and oil/chemical components drove the PPI as oil prices retreat from earlier highs. Authorities signaled more fiscal spending but stopped short of a major stimulus.
June's producer price index fell 0.3% on energy-driven weakness, led by a roughly 12% plunge in gasoline, while the core PPI rose 0.2%; the drop follows a 0.4% CPI decline and signals easing inflation ahead of possible Fed rate moves, with annual PPI around 5.5% and energy softness contributing to the cooler price backdrop.
U.S. headline producer prices fell 0.3% in June—the first monthly drop since August 2025—driven by a 6.4% month‑to‑month decline in final-demand energy goods, while the core PPI rose 0.2%. Year over year, headline PPI was up 5.5% and core PPI 4.7%. The softer print suggests the Fed may have room to postpone immediate rate hikes, but oil-price volatility and renewed geopolitical tensions (notably around the Strait of Hormuz) could push inflation back higher in July.
US wholesale prices rose 1.1% in May, lifting the annual Producer Price Index to 6.5%—the highest in more than three years—driven largely by oil-price spikes tied to Iran. A core PPI rose 0.4% (4.9% annually), and excluding food and energy, the index climbed 0.8% for a four-year high. While wholesale costs don’t always pass directly to consumers, economists say inflationary pressures could continue weighing on households as gas prices stay elevated.