Google has released Android 17 QPR3 Beta 1 to Pixel devices, addressing 20 specific issues including fingerprint freezes, eSIM failures, and Wi-Fi connectivity problems. The update targets the Pixel 6a through the Pixel 11 series, with a stable release expected in March 2027.
Boeing is developing a permanent software fix for a 737 MAX glitch that can disable automated flight guidance during specific landing scenarios. The issue, disclosed to operators in August, has triggered an FAA review and caused airlines to reject new deliveries.
Adobe posted a solid Q3 beat with $6.13 per share on $6.76 billion revenue, but the stock fell as investors weigh AI competition in creative software and a looming CEO transition, even as the company nudged its full-year revenue outlook higher; shares are down about 29% year to date.
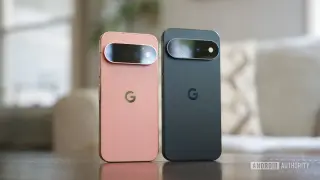
Pixel 11 Pro and 11 Pro XL are imperfect but highly usable flagships, offering standout cameras, refined hardware, and Google’s best-in-class software, making them compelling daily drivers. Drawbacks include HiLight feeling undercooked, Proactive Assistance rarely useful, and slower/quirky charging. The Tensor G6 is efficient and snappy but not a major upgrade in raw performance. Battery life and display are strong improvements, and built-in magnets add convenience. At $1,099 and $1,299 they’re worth buying for Pixel fans who value software and camera versatility, though upgrading from the Pixel 10 Pro isn’t essential and rivals like the Galaxy S26 Ultra pose strong competition.
Software stocks led gains in August—IGV up over 16%—while chipmakers lagged, with SOXX up only about 1% and late-month declines wiping roughly $1.1 trillion from semiconductor group value. Leaders like Atlassian, Palantir, Salesforce, ServiceNow and CrowdStrike surged, cementing a record software rally that widened a divergence from hardware. Looking ahead, history suggests September tends to be tougher for both the broader market and semiconductors: software has historically posted a median gain around 1% through mid-September, then softens; the S&P 500 often slides and volatility rises, making this August strength a potential headwind for the month.
Labor Day sales are flooding the music-technology scene, with major discounts on hardware from Sequential, ASM, Moog and Waldorf at Perfect Circuit and Sweetwater, plus DJI Mic Mini deals; software promotions include Isotonik Studios’ birthday sale, AAS Chromaphone 3, Soundtoys bundles for students, and Moog bundles via Plugin Boutique, all with deadlines around August 30–31 or early September.
Nissan and Honda announced a joint effort to pool software development resources for vehicles, aiming to speed up in-car software platforms and cut costs. The collaboration signals a strategic push to stay competitive as automakers increasingly rely on software and connected services, though details on scope and implementation remain limited.
A wave of strong software earnings is easing months of AI-induced fears that the sector would shrink via fewer subscriptions. Salesforce’s solid results helped the IGV ETF turn positive year-to-date, buoying hopes for a longer rally as Workday, CrowdStrike, and ServiceNow also posted momentum from AI offerings and data advantages. Analysts say the rally could extend into October, driven more by investor positioning and stock-specific fundamentals than a universal industry-wide shift.
Nvidia’s strong results underscore ongoing AI demand, but the tech rally is splitting into winners and laggards: software stocks rebound and Nvidia climbs while peers like Marvell slide, Alphabet faces AI-infrastructure headwinds, and hyperscalers’ massive capex could face spend bottlenecks from labor and supply constraints, forcing investors to differentiate winners from losers even as acceleration remains the central theme.
Workday stock rose more than 18% after Reuters reported that private-equity firm Silver Lake is in talks to acquire the HR software maker. Discussions are said to be ongoing, with the stock briefly pushing Workday’s market value above $50 billion. The move comes as investors weigh AI disruption risks to software business models; Bhusri became CEO in March, and Workday had beaten May guidance, though the shares are about 7% lower year over year amid the AI shift.
MacBooks auto-update by default, but you can disable automatic updates. Skipping major macOS updates means missing new features and critical security patches, and can break app compatibility and services like iCloud. Minor updates (e.g., 26.1) patch bugs and boost performance, but delaying major upgrades leaves you exposed to vulnerabilities. Apple typically releases annual major updates (often in September–October) and supports Macs for about eight years; older Intel Macs may lose security support sooner. For most users, staying reasonably current offers the best balance of security and functionality, though you can delay updates on very old hardware if needed.
JAM Software is ending updates and support for TreeSize perpetual licenses after their maintenance period unless customers subscribe, and won’t provide license keys or installers for expired licenses. The company says the shift to subscriptions ensures long-term development and security amid tougher economic conditions. TreeSize Personal remains a perpetual option with 12 months of updates, but business editions have moved to a subscription model. Users critique losing access to installers for owned software, though JAM notes customers are warned to back up files and keys; refunds aren’t offered since the version already paid for remains usable. A free version exists with limited features, illustrating the broader software subscription trend.
Software stocks tumbled after IBM’s preliminary results missed estimates, signaling a broader capex shift from software to hardware amid a global memory shortage fueling AI infrastructure costs; the move suggests near-term revenue headwinds for the SaaS/consulting space, with peers like Accenture, ServiceNow, Workday, Salesforce, SAP and Adobe among the notable decliners.
ETF Action’s Mike Akins says software and cloud names, coupled with overlooked small- and mid-cap stocks, could drive gains in the second half as the Magnificent Seven lagged early on; early signs show a potential catch-up rally with expanding multiples so far this year.
California lawmakers advanced tax measures within a $356 billion state budget, extending a health-care provider tax to private insurance plans (potentially about $2 billion annually and premium increases around $100 a year for individuals or $400 for a family of four) and adding a software sales tax projected to raise about $900 million annually. Republicans criticized the move as worsening costs, while Democrats argued it’s needed amid federal revenue losses, with Gov. Newsom expected to signinto law.